Grexit Theme a strong performer
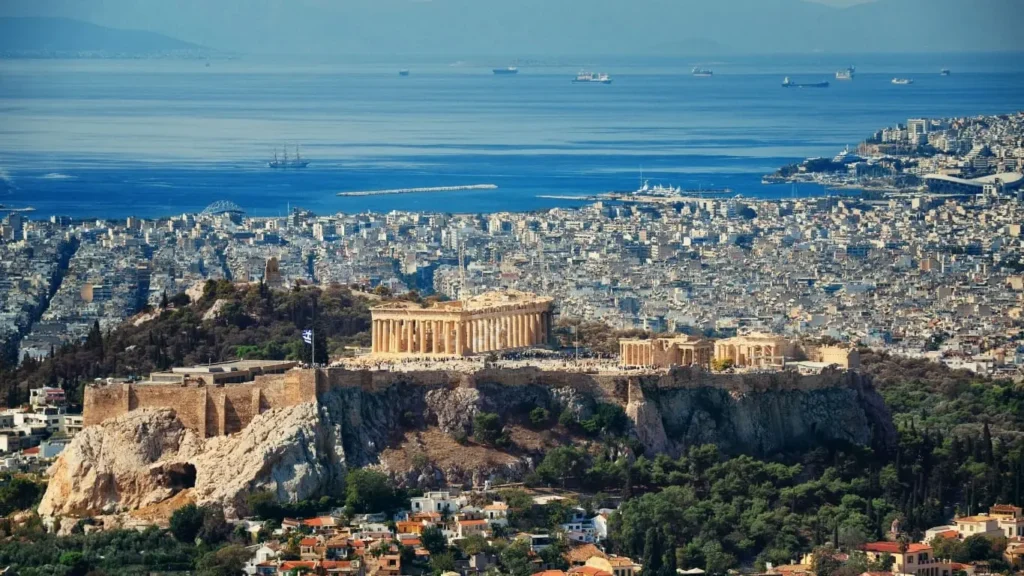
Long term readers may recall how we started studying the oversold Greek property market back in 2015-6 for a possible reversal bounce. Thanks to the confidence and trust of a small band of believers, we launched on this investment theme starting 2017, and the market has been very much a one way rising streak for us:

We first started buying in 2017 and first began taking profit in 2023 (slightly early but not a bad call given the still bloated bureaucracy dogging some of our exits – a story for another time!). In USD terms we also caught the bottom of the cycle (red line below), and began selling when prices exceeded the GFC peak in Euro terms (blue):

Given the brewing of another bigger sovereign debt crisis in Europe, and the worsening geopolitical outlook (Greece could perversely benefit as a fringe region and receive fleeing capital from neighbouring conflict jurisdictions, so may not be all bad), now is a time to close out this theme, until the coast is clear for us to revisit Greece next cycle.
Relative winner too, not just absolute gains
We are happy to also see how the Greek market gained significantly more than many mainstream property peers from the 2017 bottom to now, eg. Athens prices are up 153% vs HK:

Against the a favourite investment of Hongkongers – London – Athens also outran by 126% in the same period:
The only exception is our current top favoured destination – Perth – Athens peaked (coincidentally when we started disposing in 2023) when we began going overweight W Australia in a big way, which has now outperformed Athens some 30%:

From frog to prince? How Greece looks now…
Macro conditions are better but probably not sustainable enough going forward, because on many factors, Greece’s recoveries are not strong enough to lead to long term continued improvements:
a) debt recovery did not reach a self balancing level before global ZIRP has turned into high interest rate environment:

Despite refrained govt spending, debt levels have still been rising (blue line below), and although GDP growth has caught up since 2020, the gap remains too large to close:

b) still large trade deficit to sustain balance of payment improvements:

c) demographic headwind remains strong – despite recent spike in immigration (red line below), the ageing population and accelerating negative natural growth rate (blue line) will pose huge challenges for productivity.

Further immigration momentum is now curtailed due to govt raising thresholds (eg the Property transfer tax backlash, see Article 4), and potentially China’s shutting of emigration routes which has provided the largest group of migrants to date (see Article 1 – How Chinese investors quietly transformed Athens – one visa at a time).
The main source of immigrants are currently tax refugees (see Article 3 – Will the last millionaire to quit socialist Britain for sunny, low-tax, Thatcherite Greece please turn out the eco-lightbulbs), but local supply challenges may continue to pressure govt to close the gates further (see Article 2).
Conclusion
So we are glad we have captured this rewarding and culturally most enriching jouring, but for the near future, it is adio (Αντίο) Athena, and thanks for all the fish…
 Chinese
 English